Digital Marketing for
Financial Services
Somebody deciding where to put their money, or who to borrow it from, spends weeks reading before they contact anybody. Two things stop them: not being able to tell whether you are properly regulated, and not being able to find out what you actually require.
Your reality
How people choose who to trust with money.
This is the most cautious buyer on the entire site, and the caution is reasonable. Everything here is about removing doubt rather than creating desire.
They arrive with a question, not a product in mind
People do not search for soluciones financieras. They search cuánto necesito para invertir, requisitos para un préstamo hipotecario, cómo abrir una cuenta siendo extranjero, or qué pasa si me atraso en una cuota. Whoever answers the question properly is the institution they think of when they are finally ready, and answering questions is also the part of this industry that carries the least regulatory risk.
The first thing they check is whether you are real
Financial fraud is common enough in this region that suspicion is the default, and a legitimate institution frequently looks no more credible online than an operation that is not. Your licence, your regulator, your registration number, a physical address and named people with verifiable backgrounds do more work than any headline. Most sites bury all of it in the footer or leave it out.
They want the requirements, and nobody publishes them
How much do I need to open this, what documents does a foreigner need, what income do you ask for, how long does approval take. Rates are often regulated and change, so they are a separate matter. Requirements are not, and publishing them plainly is the closest thing this industry has to a price list. It also saves your team the calls from people who were never eligible.
For advice, they are choosing a person
For lending and wealth in particular, the institution gets shortlisted but a named advisor is what closes it. Qualifications, how long somebody has practised, what they specialise in, what they look like. An institution with no visible humans asks somebody to hand their savings to a logo, which is a great deal to ask in this market.
What goes wrong
The four mistakes we see most in financial services.
The first three cost you clients. The fourth can cost you a great deal more than that.
Language that says nothing
Soluciones financieras integrales, respaldo y confianza, tu aliado estratégico. Every competitor uses the same phrases, which means none of them differentiate and none of them answer a question anybody asked. Plain description of what a product is, who it is for and what it requires reads as competence in an industry where vagueness reads as evasion.
Regulatory standing hidden in the footer
The licence, the regulator, the registration number and the legal entity are the strongest trust assets you own, and they usually appear in small grey text at the bottom of the page if they appear at all. Somebody deciding whether you are legitimate should not have to hunt for that. Put it where the doubt is.
Forcing a branch visit to learn anything
No requirements, no document list, no indication of timeframes, just a form asking somebody to be contacted by an executive. That was a reasonable design twenty years ago. Today the person simply reads a competitor who published the answers, and you never learn that they were interested.
Promising returns or approval
Guaranteed yields, approval regardless of history, projections presented as expectations, testimonials that read as investment advice. Beyond the regulatory exposure, which is real and varies by country, this is exactly the language people associate with the schemes they are afraid of. Describing a product honestly, including its risks and who it does not suit, converts better and is defensible.
What we would start with
For a financial business, in this order.
This is the one industry where paid advertising comes last rather than first, because the restrictions are real and the groundwork has to exist before any of it is worth buying.
1 · SEO
A page for every question your clients ask before they are ready, and a proper page per product with its requirements. Informational content is rarely restricted anywhere, which makes it both the safest and the most productive place to start in a regulated industry. It is also what an assistant reads when somebody asks about your product category.
2 · Diseño Web
Regulatory standing where the doubt is rather than in the footer, profiles for the advisors people will be dealing with, requirements and document lists published per product, and a site that handles personal information the way somebody nervous about fraud expects it to be handled.
3 · Redes Sociales
For fintech and for advisors reaching younger clients this matters, and what works is explanation rather than promotion. It also carries the highest compliance risk in the industry, since a casual post can read as advice. Everything published goes through whatever approval process you already have, and we build for that rather than around it.
4 · Google Ads
Financial advertising requires verification on the platforms, faces category restrictions that differ by country, and carries some of the highest costs per click anywhere. It works, on specific high value products, once the pages and the credentials behind it are in place. Spending here first is how budgets disappear in this industry.
AEO · being the answer when somebody asks
Financial questions are among the most common things people now put to an assistant, precisely because they are embarrassing to ask a person: what a term means, what a mortgage requires, whether an account is available to a foreigner. The answer often names institutions.
Assistants are careful with money questions and lean on sources that look authoritative and clearly structured, which favours institutions that publish real explanations and verifiable credentials. The work that makes you citable is the same work that reassures a nervous human reader.
What changes
What working looks like for you.
These are the things we report on, because they are the things we control. We do not promise client numbers, deposits or loan volume, and in this industry you should be particularly wary of anybody who does.
You appear for the questions before the product
Rankings on the questions people ask months ahead as well as on the product terms themselves, reported separately, because the first group is where the relationship starts and it is usually the part nobody is competing for.
Enquiries are counted by product
Form submissions, calls and applications started, tracked by product and by page, so you can see whether mortgage enquiries are growing while personal lending sits flat. Where your process moves offline we agree how to record what happened next.
More of your visitors get in touch
Published requirements, visible regulatory standing and named advisors change how many existing visitors contact you at all. Measurable from the week the changes go live, before new traffic arrives.
What somebody finds when they check you
What appears when a cautious person searches your name, including reviews and any old complaint threads, monitored and answered properly. In an industry where the first move is verification, this is reported as carefully as rankings.
Get a market snapshot for your institution
Before any talk of scope or price, we will pull what people in your market search for around your products, question by question and product by product, roughly how many of them there are each month, who currently holds those positions, and where the realistic gap is. Written up and sent to you. No charge.
Where we deliver
Financial services, in your market.
An institution in Panama serves a market built around international banking, with a large share of enquiries arriving in English from people who do not live there. An institution in Colombia works in a market where digital financial services have grown quickly and where a great deal of the demand comes from people opening their first formal product. Rules, language and expectations all change with the border.
Questions
Frequently asked questions
Are we allowed to advertise financial products?▾
Can we publish our rates?▾
We are a crypto business. Can you work with us?▾
Everything we publish has to go through compliance. Does that work?▾
We are small. How do we compete with the large banks?▾
Does social media actually work in this industry?▾
How long before I see results?▾
Who would I actually be working with?▾
Who you deal with
You will be working with Aylin.
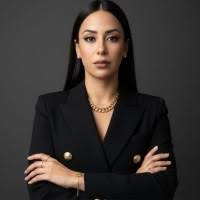
Aylin spent her career in marketing and in enterprise marketing software sales, working with major brands and companies throughout Latin America. She has sat across the table from marketing directors defending a budget and reporting results upward, which means she already knows what a plan has to look like before anyone can say yes to it.
That is why a first conversation with her feels closer to a diagnosis than a pitch. She will want to know which products you want more of, where your clients find you today, and what your approval process looks like. Then she will tell you which of the five services would change things fastest, including when the answer is that you do not need all of them.
She works in Spanish or English, whichever you prefer, and inside your business hours. She handles your account herself from that first message through to the monthly reviews, so nobody hands you to a junior once the contract is signed.
Let us look at your market first.
Tell us which products you want more of and where you are licensed. You will get back a snapshot of what people in your market are searching for, who currently comes up, and what it would realistically take to be the institution they find.
Request your market snapshot →